


Affirm: Buy now, pay over time
4.8222.44K Reviews
App Specs
- Version
- 4.89.1
- Updated On
- License
- Free
- Downloads
- 10,000,000+
- Developer
- Affirm, Inc
- Categories
- Shopping
- Platform
- Android, iOS
Screenshots
 Analysis by AppCompare
When I consider a buy-now-pay-later app, I care about more than whether it gets me through checkout. I want to know if I can understand the cost, keep track of what I owe, and use the app comfortably when I’m shopping in different ways. Affirm is a free shopping app from Affirm, Inc. that puts installment payments at the center of the experience. It has a 4.8 average from around 541,000 ratings, and more than 10 million installs. Those figures suggest a well-used service, but the practical question is whether its payment flow fits your habits and your budget.
Finding your way around payment choices
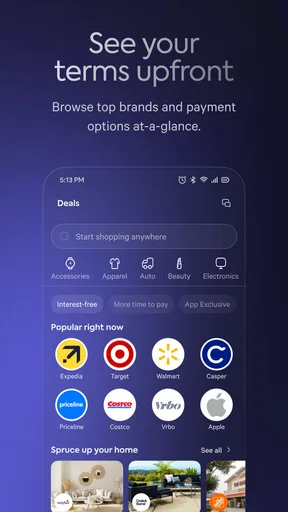
For me, the most useful part of a payment app is being able to pause and review the commitment before I agree. Affirm’s appeal is that it presents a purchase as a set of payments rather than leaving me to work out the schedule later. In the original shopping experience, the total interest is shown upfront, which makes the decision easier to evaluate than a vague promise of smaller installments. I’d still read the complete offer each time: payment terms can be tied to the purchase, and a plan that suited one order may not suit the next.
The interface is described as intuitive, and that matters for people who do not want to learn a complicated finance tool just to make a purchase. I would approach the screens deliberately rather than tapping through quickly: check the total, the timing of payments, and the amount due before confirming. If you’re comparing several items, write down or otherwise keep a simple view of each commitment before adding another. That small pause can make a multi-purchase decision easier to understand than relying on memory.
Reading the commitment, not just the installment
An installment amount can feel manageable on its own while several plans together take a meaningful share of a future paycheck. I’d judge affordability against the full repayment schedule, not just the first payment or a monthly figure. This is especially important for irregular income: a plan that looks comfortable in a good week may be awkward when hours or earnings change. The upfront cost breakdown is useful, but it does not replace making your own budget.
Compared with paying directly by debit, Affirm can spread the cost instead of taking the full amount at once. Compared with a credit card, it gives the purchase a more explicit payment schedule, which some people may find easier to follow. Neither comparison makes installments automatically cheaper or safer. A card may be simpler for someone who pays the balance in full and prefers not to manage another account; paying upfront may be best when the purchase is optional or cash is already available.
Motor, sensory, and everyday access
A straightforward interface can lower the effort involved in checking an order, but it cannot tell me whether every screen will work equally well for every person. If fine taps or long sessions are tiring, I’d handle the review and confirmation steps when I have time, rather than in a rushed checkout line. Where a screen is hard to read or operate, the device’s own display and input settings may help, though the result depends on the device and app version. I would not assume that a payment decision is accessible simply because the main flow feels simple to me.
Shopping also happens in distracting places: on a bus, between errands, or while juggling bags at a store. For a consequential choice, I prefer a quiet moment and a stable connection, with enough time to inspect the terms instead of approving them while distracted. Notifications about upcoming payments can help keep a plan visible, but they are a reminder aid rather than a substitute for checking that the schedule fits. If alerts are easy to miss in your day, use a separate calendar or budgeting routine as a backup.
Worth Reading Before You Choose

EA SPORTS FC Mobile 26 Is a Bigger Football Game, but It Takes Time

Flipboard Shows What News Apps Must Do Beyond the Feed

Switching to Android Auto Means Rethinking Your Driving Routine

Google Calendar Makes a Crowded Week Easier to Manage

Ludo King Makes the Most of the Minutes Between Plans

Baby Panda World Brings Quick Play to Modern Phones, but Its Game Library Feels Busy
Where the convenience has limits
Affirm is most compelling when a necessary or carefully planned purchase is too large to pay all at once and the specific offer fits your finances. It is less suitable for impulse shopping, for purchases that can wait until you have saved, or for anyone who finds multiple due dates stressful. The app’s free download does not mean every payment plan is cost-free; review the exact terms presented for your purchase rather than assuming all offers work the same way.
It also helps to distinguish the payment app from the retailer’s shopping experience. A store’s availability, checkout flow, and delivery arrangements are separate parts of buying the item, so I would check those details with the retailer before committing. If a checkout option is not offered for the purchase you want, a normal card or direct payment may be more straightforward than changing your shopping plans around installment financing.
Who is likely to find it useful?
I can see Affirm working well for someone who plans purchases ahead, wants a visible repayment schedule, and is comfortable tracking more than one obligation. For example, if a household appliance needs replacing just before payday, I’d compare the full plan with the cost of waiting, check that the future payments leave room for essentials, and only then decide whether spreading the expense is worthwhile. That is a better use than treating an available plan as extra spending money.
Someone who prefers cash or debit, has an unpredictable budget, or tends to forget recurring obligations may be better served by saving first or using a familiar payment method. The same goes for shoppers who want one place to manage every financial account: Affirm is focused on its own purchases, not a complete household budgeting system. Before relying on it for a time-sensitive purchase, check the offer and checkout while you still have another way to pay.
App details and my inclusive verdict
Affirm is rated for Everyone, was released on June 20, 2016, and its current version is 3.402.1 for devices running Android 7.0 or later. Those details make it easy to judge basic compatibility, but they do not settle whether the app’s screens or payment flow suit your individual needs. I’d test the parts you expect to use—especially reviewing a plan and locating payment information—before depending on it for an important purchase. Its 213,000 reviews also show that many people have shared feedback, though a large review count cannot predict your own experience.
My overall view is that Affirm can make a planned purchase easier to pace, provided I treat the schedule as a real financial commitment and not as a discount. Its clear cost presentation and payment reminders are practical strengths; the need to keep track of combined obligations is the central trade-off. I’d recommend trying it only when the particular offer makes sense in your budget, and I’d skip it when paying later would turn a want into a strain. The app is a tool for organizing payment, not a reason to buy more.
Getting Started with Affirm
Jumping into Affirm is a breeze. After downloading the app, setting up an account took me all of five minutes. You simply verify your phone number, enter some basic info, and voilà—you’re in! The app interface is super intuitive, so even if tech isn’t your best friend, you won’t get lost here.
Shopping Made Easy
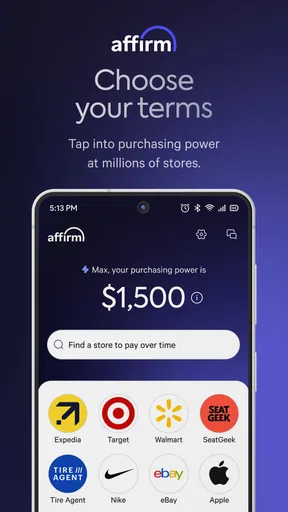
Now, the fun part—shopping! Affirm partners with tons of retailers, from electronics to fashion, so the options are endless. You can browse directly from the app or use it at checkout on partner sites. I ended up snagging a pair of headphones I’d been eyeing. Using Affirm at checkout was seamless; just select it as your payment method, and boom—you’re good to go.
Flexible Payment Plans
What I really dig about Affirm is its flexible payment plans. You can choose to pay over 3, 6, or even 12 months. They lay out the total interest upfront, so there are no hidden fees lurking in the shadows. For my headphones, I opted for a 3-month plan. The clear breakdown of payments made it easy to budget.
User Experience
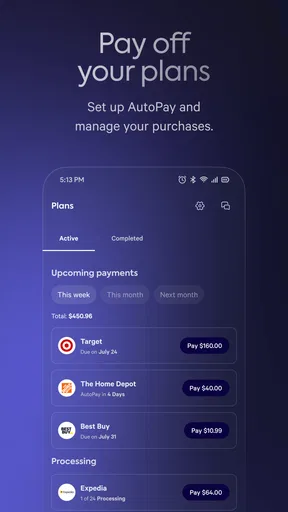
Throughout my experience, the Affirm app ran smoothly. I received timely notifications about upcoming payments, which is great for avoiding any surprises. The app also has a handy feature to manage multiple purchases, so if you’re a shopaholic like me, it’s easy to keep track of everything.
Is Affirm for You?
So, is Affirm worth a shot? If you’re looking for a way to spread out payments without racking up credit card debt, this app’s a gem. It’s especially useful for larger purchases where you might need a bit more flexibility. However, remember to always spend within your means—those monthly payments add up quickly!
All in all, I’d say give it a try. With a user-friendly interface and transparent payment plans, Affirm makes buying what you love a whole lot easier.
Pros
- Flexible payment options for budget management.
- User-friendly interface for easy navigation.
- No hidden fees or surprises in payments.
- Quick approval process enhances convenience.
- Secure transactions for peace of mind.
Cons
- Limited to participating retailers only.
- Interest rates can be high depending on credit.
- May impact credit score with missed payments.
- Not available for all purchase categories.
- Requires personal information for account setup.
FAQs for Affirm: Buy now, pay over time
What is Affirm and how does it work?
Affirm is a financial service app that allows users to purchase items now and pay for them over time through installment plans. After selecting Affirm at checkout, you can choose a payment plan that suits your financial situation. Payments are made over a set period, often with clear, upfront terms and no hidden fees.
Does using Affirm affect my credit score?
Using Affirm can affect your credit score. When you apply for a loan through Affirm, they perform a soft credit check that doesn’t impact your score. However, if you miss payments, it could negatively affect your credit. Keeping up with payments can help build your credit history positively.
Are there any interest rates or fees with Affirm?
Affirm offers transparent financing with no hidden fees. Interest rates can vary from 0% to 30% APR depending on your creditworthiness and the merchant, and all terms are clearly presented before you agree. It's important to review the terms carefully to understand the total cost over time.
What payment options are available with Affirm?
Affirm provides flexible payment options that typically range from three to 36 months, depending on the purchase amount and your eligibility. You can manage payments through the Affirm app or website, and they accept bank transfers, checks, and debit cards for installment payments.
Is Affirm available outside of the United States?
Affirm is primarily available to users within the United States. While they are expanding services, availability may vary by country. It's crucial to check their official website or app for the latest updates on international availability and any specific terms for different regions.


